After the Tow: Will You Get Your Car Back, and Will It Be Safe?

Car Towing Scams
Unexpected storage fees. Missing parts. Repairs that look convincing but leave unanswered questions. Here is what vehicle owners should check after an accident in South Africa, with lessons from overseas.
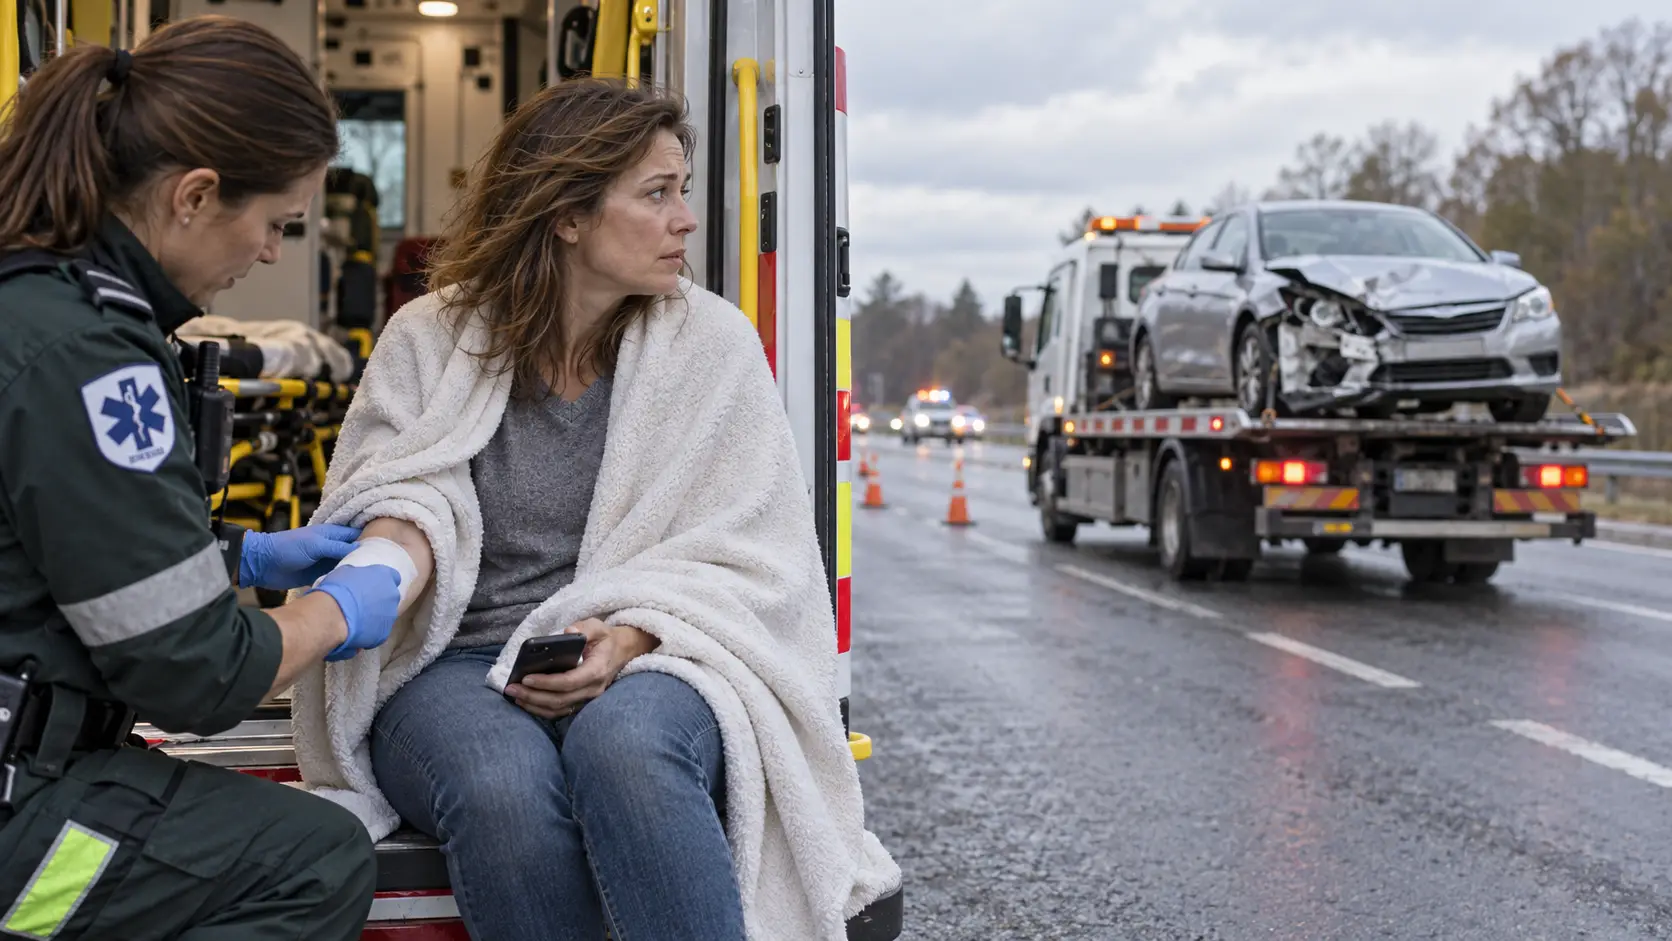
The accident is over. Your vehicle is on a tow truck, and someone tells you they will take care of everything. In that moment, getting home or receiving medical attention matters more than asking about storage charges, repair authorisation or who will have access to your car. Days later, those questions can become urgent: Where is my vehicle? Why is the bill increasing? What have I authorised? And will the car I get back be safe?
I have experienced that uncertainty myself. After an incident involving my own vehicle, I discovered that parts had been removed for installation on another car. Fortunately, I had taken photographs that helped me substantiate what had happened. Getting my vehicle back still took three months and considerable effort. That experience is why I believe the questions owners ask after towing deserve as much attention as the accident itself.
The Second Problem
Professional towing operators and repairers provide essential services. Charging for recovery, secure storage and skilled repairs is not inherently suspicious. The concern is what happens when costs are concealed, consent is misrepresented, explanations keep changing or the vehicle’s condition no longer matches the records.
These are documented concerns, not merely hypothetical ones. In January 2020, South Africa’s Consumer Goods and Services Ombud reported complaints alleging false insurer authorisation, undisclosed towing and storage charges, refusal to release vehicles, and stripping or vandalism while vehicles were in custody. The warning records allegations received by the ombud; it does not establish that these practices describe most operators. Read the CGSO warning.
Before It Leaves
Your safety and medical needs come first. Do not enter traffic, approach an unstable vehicle or delay emergency treatment to collect evidence. If you are able to make arrangements safely, contact your insurer or roadside-assistance provider using the number in your policy or official app. Do not rely solely on someone at the scene saying they have obtained approval.
Ask for the operator’s details, the destination and written charges. Photograph the vehicle and tow truck when safe, and retain a copy of anything you sign. The AA recommends these precautions and recognises that police or emergency personnel may arrange towing when a driver is incapacitated. AA towing guidance.
Follow The Vehicle
Do not assume the towing company, storage yard and repairer are the same business. Establish who currently holds the vehicle, the exact address, who is responsible for communicating with you, and whether it has moved since collection. Confirm the destination with your insurer where a claim is involved.
A useful first request is a written account of the vehicle’s location, its arrival date, its recorded condition, the services authorised and the charges incurred so far. Keep the reply alongside the towing paperwork. Unexplained transfers or conflicting accounts deserve clarification, although they do not by themselves prove wrongdoing.
Understand The Charges
The initial towing price may not explain the whole bill. Ask whether the quotation includes recovery work, distance charges, storage, administration, after-hours release and any subsequent transport. For storage, establish the daily rate, when it starts, how days are counted and what stops further charges.
Request an itemised invoice rather than accepting a single unexplained “release fee”. Ask which agreement or authorisation supports each disputed charge. Do not assume your insurer will pay every amount demanded: obtain confirmation directly about what it has authorised and what your policy covers.
Getting It Back
A demand for payment before release is not automatically evidence of theft or a scam. Operators may assert a lien, a claimed right to retain the vehicle as security for payment. The AA’s own published towing terms include a lien provision, illustrating why the agreement matters. Whether a particular claim is enforceable requires assessment of the facts and applicable law. AA towing terms.
If release is refused, ask for the reasons and claimed balance in writing, notify your insurer promptly and obtain legal advice where necessary. Do not attempt to remove the vehicle by force. Equally, do not assume that lodging a complaint automatically freezes storage charges or secures immediate release.
Authorising The Repairs
Permission to tow should not be treated casually as permission for every subsequent service. Check what your paperwork actually authorises, including assessment, dismantling, storage and repairs. Before work begins, request a written scope, estimate and explanation of how additional damage or costs will be handled.
South Africa’s Consumer Protection Act regulates repair authorisation under section 15. It addresses estimates, recorded authorisation and approval for additional charges. Assessment or dismantling work used to prepare an estimate can also carry costs that need clarification beforehand. RMI consumer-rights guidance.
Account For Parts
A removed component is not necessarily a stolen component: legitimate assessment and repair work may require dismantling or replacement. The important questions are what was removed, why, who authorised it, what replaced it and where the original went.
Request a parts record showing descriptions, identifying numbers where available, and whether replacements are new, reconditioned or used. Section 67 of the Consumer Protection Act generally requires removed parts to be retained separately and returned unless the consumer declines. Exceptions include certain insurer, warranty and regulated-disposal requirements. Ask what applies to your repair rather than assuming every component must be handed back. Consumer Protection Act, section 67.
Beyond The Paint
A car can look substantially better without its appearance establishing that the entire repair is complete. Collision damage can involve structural components, steering, suspension, restraints, wiring and electronic safety systems. What requires inspection, replacement or calibration depends on the particular vehicle and impact.
I-CAR, a collision-repair training organisation, explains that hidden damage and electronic faults may not be visually apparent. Its guidance emphasises manufacturer-specific repair information and the calibration of relevant driver-assistance systems. A smooth panel or clear dashboard is not a substitute for the required checks. I-CAR technical guidance, calibration guidance.
What “Approved” Means
“Approved repairer” needs a second question: approved by whom? Insurer approval, vehicle-manufacturer approval and industry-association membership are different claims. Verify the current status with the organisation concerned, including whether it covers the relevant branch, vehicle brand and work.
South Africa’s Competition Commission distinguishes insurer and manufacturer approval in its automotive aftermarket guidelines. Its September 2024 guidelines also address allocation of insured, in-warranty vehicles to manufacturer-approved motor-body repairers. Approval is relevant evidence, but it does not independently establish that every step on your particular vehicle was completed correctly. Competition Commission guidelines.
Request Repair Evidence
Instead of accepting “repaired to factory standards” as a complete answer, ask what documents support it. Depending on the damage and manufacturer’s requirements, relevant records may include the repair scope, parts invoice, structural measurements, wheel-alignment results, diagnostic scans, calibration results and final quality-control checks. Not every vehicle needs every procedure.
Where serious doubts remain, discuss an independent inspection with your insurer and a suitably qualified collision-repair assessor. Agree the inspection’s scope and cost beforehand. Photographs and desk research can identify questions; they cannot certify hidden workmanship or establish roadworthiness. Do not drive a vehicle you reasonably suspect is unsafe merely to test whether the problem returns.
Preserve Your Evidence
Keep original photographs and videos, not only compressed copies sent through messaging apps. Record dates, locations and who supplied each document. Preserve quotations, signed authorisations, job cards, invoices and correspondence. A simple timeline can reveal where the explanation changed or a promised update never arrived.
If components appear missing, document the discrepancy and request a written explanation before drawing conclusions about who removed them or why. Suspected theft or fraud should be reported to SAPS. Avoid publicly accusing a named business before the evidence has been properly reviewed.
Lessons From Overseas
The same combination of urgency, unfamiliar providers and accumulating charges appears internationally. Texas’s Department of Insurance warns about unsolicited tow operators directing accident victims to particular repair shops, followed by substantial storage and other fees. Its advice includes verifying the operator and reading documents before signing. Texas insurance-regulator warning.
Western Australia has introduced crash-towing reforms to address misconduct and price gouging. The first stage commenced on 10 January 2025, including maximum charges for specified crash-towing and storage services in Perth and Peel. Its consumer guidance also warns that storage costs can accumulate during disagreements between operators and insurers. Transport WA reforms, consumer guidance.
These examples demonstrate that the risks cross borders. The laws do not. Overseas fee caps, authorisation rules and complaint procedures should never be presented as rights automatically available in South Africa.
Where To Escalate
Start with a clear written complaint to the responsible business, identifying the disputed charges, missing information or repair concerns and the outcome you seek. For unresolved automotive disputes, MIOSA provides a complaint process; its service is generally free, although an inspection may be for the consumer’s account. MIOSA complaint guidance.
For a dispute with your insurer, complain to the insurer first, then approach the National Financial Ombud where appropriate. NFO provides free dispute-resolution services within its jurisdiction. Neither an ombud complaint nor a research report replaces urgent legal assistance when a vehicle is being withheld or threatened with disposal. NFO complaint information.
When Doubts Persist
Perhaps the vehicle has already been towed. The company’s explanations do not match the paperwork, claimed approvals are unclear, or you have found complaints that sound disturbingly familiar. At that point, the need is not another reassuring promise. It is a clearer understanding of the business, its claims and the available evidence.
An AdUncovered Comprehensive Report can research the provider’s public business history, claimed affiliations, relevant complaints and available public findings, alongside the information you provide. It can help identify contradictions and unanswered questions and organise source-linked findings for your next conversation with an insurer, assessor, ombud or attorney.
It cannot physically inspect your vehicle, certify repair quality, determine criminal guilt or guarantee release or compensation. Those boundaries matter. Getting your car back is one concern. Understanding what happened to it, what you are paying for and whether further technical checks are needed matters just as much.
Check before you pay
About to pay a seller or business you don’t know? Start with a Free Quick Check of the advert link. It screens for common warning signs and shows where each result came from.
If you need the seller researched, a Quick Report or Comprehensive Report brings together source-linked Search Results on the seller and the offer. Neither gives a verdict: you check the sources and decide for yourself.
This article provides general consumer information, not legal or vehicle-safety advice. Rights, insurance cover and repair requirements depend on the circumstances and jurisdiction. Sources checked on 6 October 2026.